
France’s proposed crypto tax changes would make a move from Bitcoin or Ether into certain stablecoins a taxable disposal, even if the investor never withdraws cash.
The National Assembly’s Finance Committee adopted amendment I-CF1826 on Oct. 7, adding that proposed exception to a broader overhaul of how private crypto gains are calculated. The provision would apply to disposals and exchanges from Jan. 1, 2027 if enacted.
For an investor selling Bitcoin exposure into USDC, the consequence would be a change in the tax timing of a risk-reduction trade. A gain could become reportable while the proceeds remain in a crypto wallet or exchange account. But the proposal also changes the cost deducted from those proceeds, and gives older holdings a transition choice.
Under French tax authority guidance, covered crypto-to-crypto exchanges without a cash balancing payment receive tax deferral. Converting into fiat or using crypto to obtain other goods or services can already be taxable under the private-disposal regime, subject to its applicable exemption.
CF1826 would remove the exchange deferral when the investor receives e-money tokens as defined by the EU’s Markets in Crypto-Assets regulation, or related rights. The operative wording targets the asset received. A swap out of Bitcoin into a qualifying token could therefore recognize a gain before any later cash withdrawal.
MiCA’s definition describes a crypto-asset that seeks to maintain stable value by reference to one official currency. That legal definition sets the exception’s scope. The amendment invokes it without an express issuer-licensing condition.
USDC provides a concrete example: Circle’s European white paper identifies it as an e-money token under the same MiCA provision. The illustrations below use native USDC, with transactions measured in euros.
The amendment’s sponsors justify the change by describing deferral on fiat-backed stablecoin conversions as a legislative loophole. For an investor using a swap to reduce market exposure, the practical effect would be earlier recognition of any gain.
The proposed tax calculation concerns the gain above cost. It subtracts the acquisition basis of the assets surrendered from the disposal price. That basis is the cost recognized for tax purposes; a transaction can produce a gain, no gain or a loss.
Two ways to value older holdings
France’s existing portfolio-based calculation allocates part of the acquisition price of the entire crypto portfolio to each taxable disposal. Current guidance deducts total portfolio acquisition price multiplied by the ratio of disposal price to portfolio value immediately before the transaction.
The proposed replacement would focus on the crypto-assets actually disposed of. For assets of the same nature purchased at different prices, it specifies weighted-average acquisition value.
For holdings acquired before 2027, the amendment offers two routes. An investor could use evidenced actual acquisition costs, determined under the new basis rules. Alternatively, the investor could allocate the portfolio acquisition price calculated under the old rules at Dec. 31, 2026 among the assets held then, in proportion to their values on that date.
The allocation option preserves a pool of acquisition cost and distributes it among holdings. The available cost pool remains the acquisition price calculated under the old rules, rather than the portfolio’s full market value. The text makes that choice irrevocable for the entire portfolio when the first return reporting a taxable disposal after Jan. 1, 2027 is filed.
Consider a hypothetical investor whose Bitcoin cost €20,000 and is worth €60,000, while their Ether cost €40,000 and is worth €40,000 at the transition date. The portfolio has €60,000 of acquisition cost and a €100,000 value. Assume no prior disposals, fees or cash balancing payments, no other holdings of the same tokens, and unchanged euro values through the transactions.
Under the allocation option, Bitcoin represents 60% of the portfolio value and receives €36,000 of basis. Ether receives the remaining €24,000. Using actual costs instead would leave their bases at €20,000 and €40,000, respectively.
The same Bitcoin-to-USDC transaction would then produce different first-disposal gains:
| Hypothetical transaction or basis | Proposed actual-cost route | Proposed allocation route |
|---|---|---|
| Bitcoin basis before the swap | €20,000 | €36,000 |
| Gain on swap into €60,000 of native USDC | €40,000 | €24,000 |
| Basis of the USDC received | €60,000 | €60,000 |
| Gain on later Ether disposal for €40,000 | €0 | €16,000 |
The table compares hypothetical gross gains under the proposal. Under the current rules, the qualifying swap itself would receive deferral. Under either proposed transition route, the Bitcoin-to-USDC swap would become a taxable event.
Changing only the historical costs to €50,000 for Bitcoin and €10,000 for Ether reverses the first-disposal comparison: actual cost would produce a €10,000 Bitcoin gain against allocation’s €24,000. The remaining Ether gain at unchanged values would be €30,000 under actual cost or €16,000 under allocation. Historical costs determine which method recognizes more gain first.
Basis resets and the cost of loss timing
The proposal expressly distinguishes exchanges that retain deferral from exchanges that become taxable. A deferred exchange carries the surrendered assets’ basis into the assets received. A taxable exchange gives the received crypto-assets a basis based on the consideration value already used to calculate the gain, adjusted for any cash balancing payment.
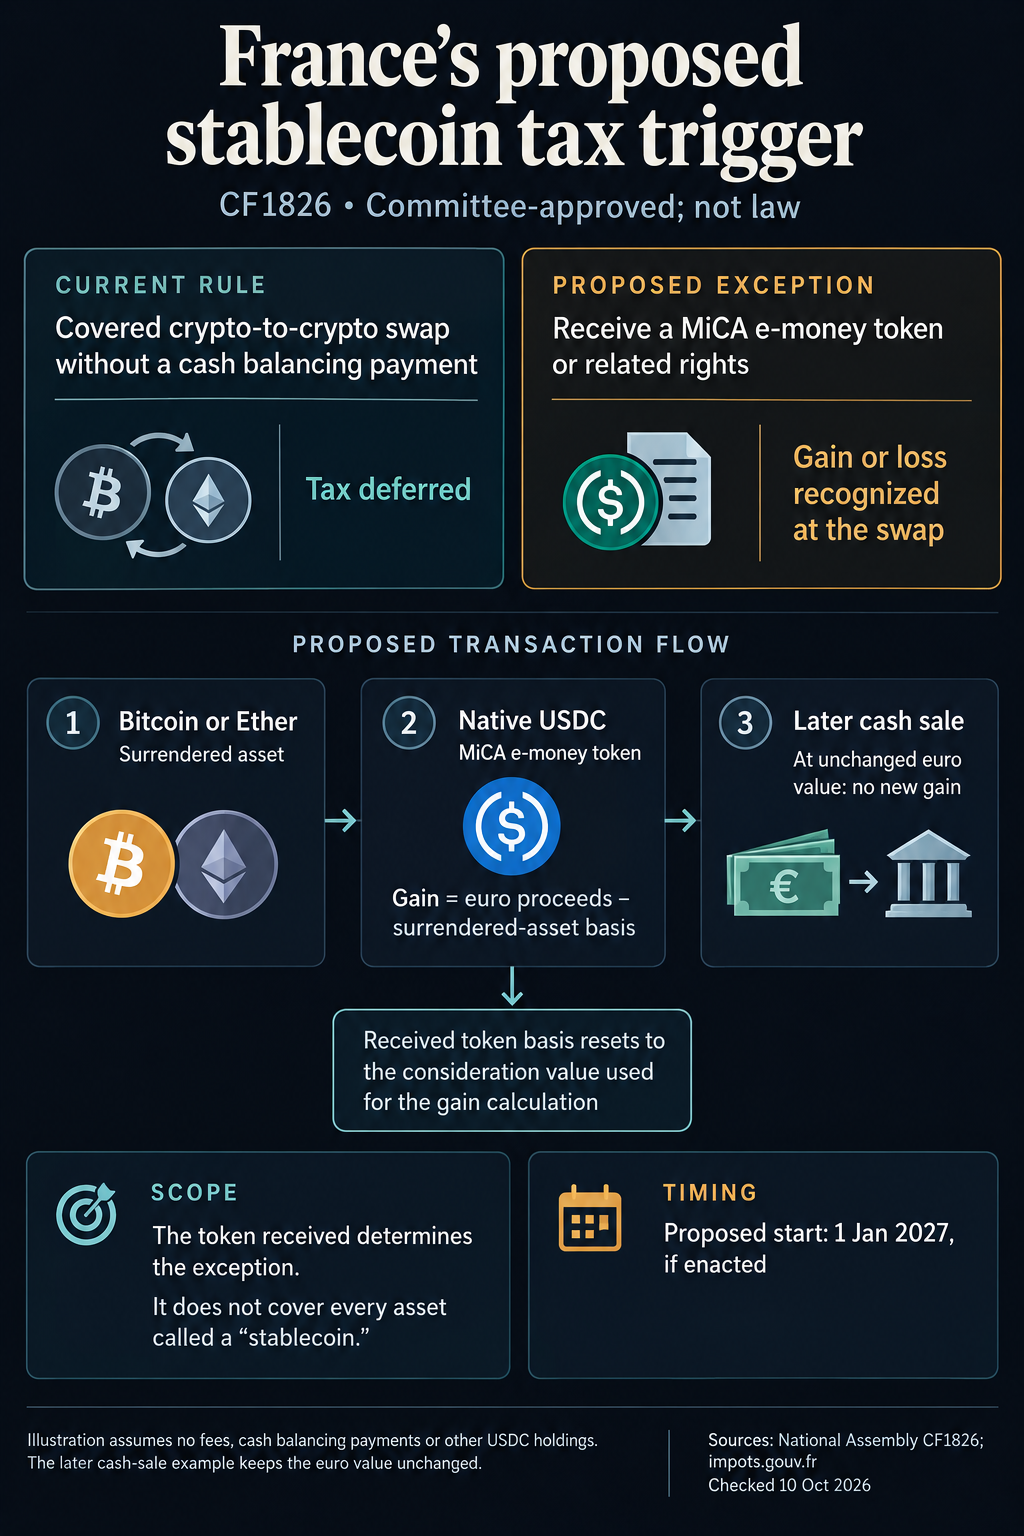
For the Bitcoin-to-USDC swap in the first example, the reset rule would give the USDC received €60,000 of basis under either transition route. Selling it later for the same €60,000 would produce no further gain. That reset would prevent repeat recognition of the original Bitcoin gain when the unchanged-value proceeds finally reached a bank account.
USDC references the dollar, so the unchanged-euro-value assumption is essential. A later disposal at a different euro value would require its own gain or loss calculation.
If the investor also sold the remaining Ether for €40,000, the first example would produce aggregate realized gains of €40,000 under either proposed transition route. Actual cost recognizes all of that in Bitcoin; allocation splits it between Bitcoin and Ether.
The amendment would change the swap exception and basis rules without rewriting the existing crypto loss restriction. The tax authority says crypto gains and losses offset within the same tax year, while a net crypto loss cannot be carried into later years or used against gains on other assets.
A separate hypothetical shows the effect of recognizing losses and gains in different years. Under the proposed actual-basis rules, a sole Bitcoin holding bought for €30,000 and swapped into €20,000 of native USDC would recognize a €10,000 loss. The USDC would receive €20,000 of basis.
If that USDC were later exchanged into Bitcoin without a cash balancing payment, the swap would retain deferral because Bitcoin is outside the received e-money-token exception. It would carry the €20,000 basis into Bitcoin. A subsequent taxable Bitcoin sale for €30,000 would recognize a €10,000 gain. Assume no fees, other token pools, cash adjustments or other gains and losses.
Those amounts could offset if realized in the same tax year. If the net loss arose in one year and the gain in a later year, the earlier loss would not shelter that later gain under the existing rule. Recognition in different years can therefore change the taxable result even when the transaction sequence returns the holding to its original value.
The reporting trade-off follows from the same mechanics. Asset-specific basis would remove the portfolio-wide allocation formula for new disposals, but investors would need to preserve acquisition evidence, weighted averages and the basis carried or reset through swaps. For older holdings, the proposed allocation route would also require a Dec. 31 valuation and a whole-portfolio decision that the text makes irrevocable.
The next legislative test remains ahead. The 2027 budget dossier, checked Oct. 12, lists National Assembly plenary discussion for Oct. 13.
Analysis,Featured,Stablecoins,Taxes,Bitcoin,BTC,Circle,ETH,Ether,ethereum,stablecoins,USDCBitcoin,BTC,Circle,ETH,Ether,ethereum,stablecoins,USDC#France #crypto #tax #proposal #targets #BitcointoUSDC #swaps1791818688
