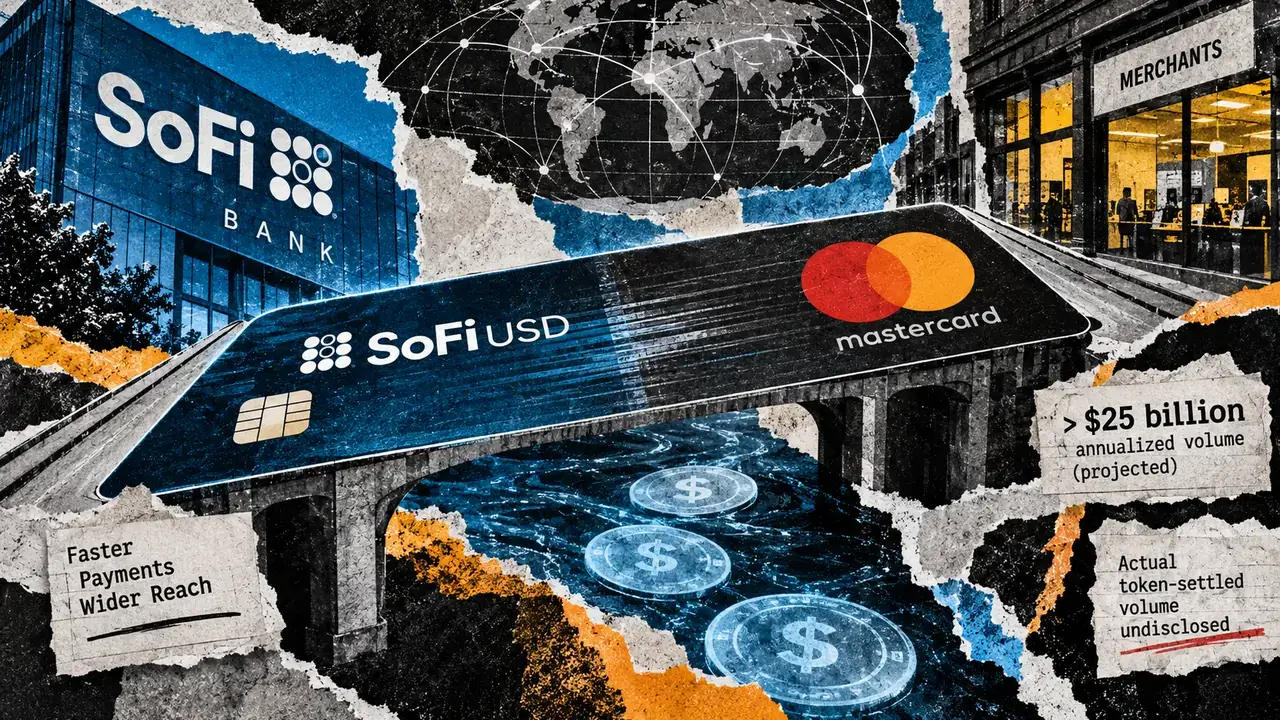

SoFi Bank and Mastercard have announced SoFiUSD settlement is live for the bank’s debit and credit card program, moving their March plan into production.
The rollout puts a token-based settlement route behind familiar card payments and, according to SoFi, gives participating merchants a way to receive dollars in a bank account without holding the token. SoFi expects more than $25 billion in annualized card-program volume after migration; it has not disclosed how much has actually settled in SoFiUSD.
The migration remains underway. Cardholders can keep using existing cards, while SoFi describes a bank-account cash route for merchants and separate redemption rules for token holders. Those groups encounter different parts of the arrangement, so a live blockchain transaction alone says little about the scale of merchant benefit or token-holder access.
From a planned rail to live settlement
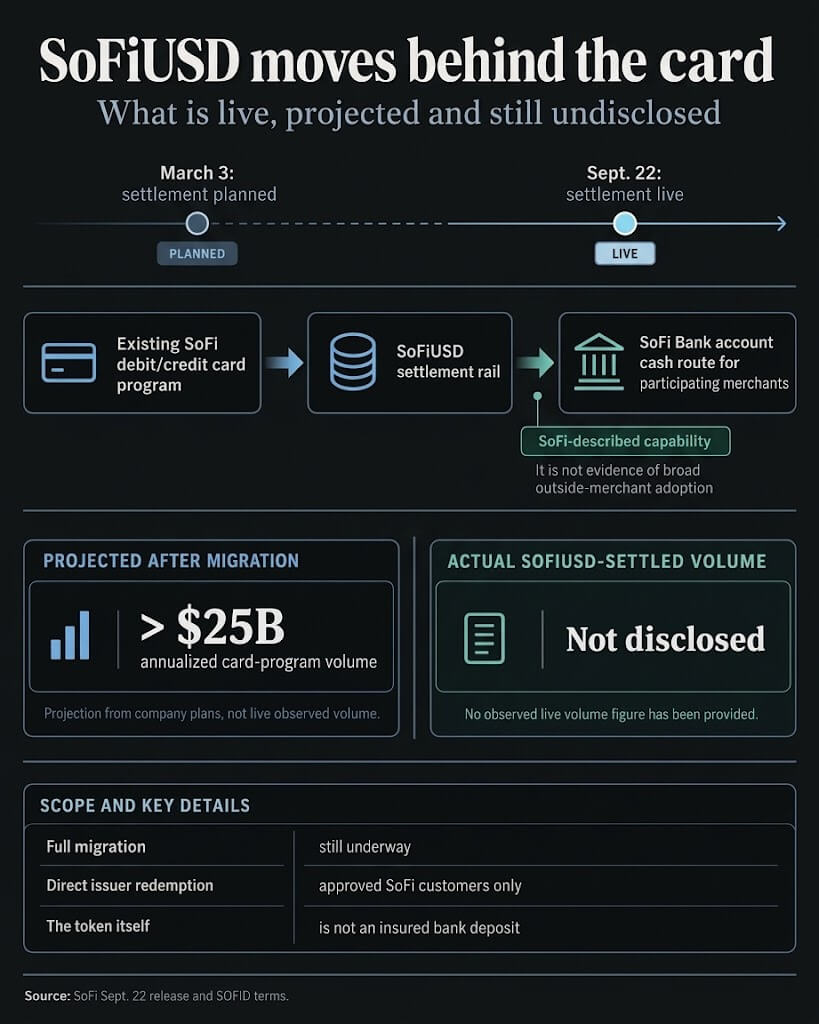
The March partnership announcement described SoFiUSD settlement as a future option. The companies’ September release says transactions are now occurring on a blockchain for SoFi Bank’s card program. The full-program migration is still in progress, and SoFi has not given a completion date.
SoFi expects the program to process more than $25 billion annually using SoFiUSD after that migration. The figure is a projection of card activity at an eventual run rate. SoFi has not disclosed the amount or share of transactions already settled in the token. That missing denominator prevents readers from treating the projected program size as the stablecoin’s observed throughput.
The token operates behind cards people already carry. SoFi says merchants need no stablecoin holdings or new infrastructure to use its proposed route, and the companies describe no requirement for consumers to acquire crypto at checkout. The visible card payment and the settlement path can therefore change on different schedules.
For merchants, the useful measure is when settlement becomes spendable cash. The September release offers no measured before-and-after comparison of that timing or of cost for this program. A working transaction establishes operating status; merchant-level results would establish the economic effect.
SoFi says businesses using its Big Business Banking platform can receive settlement funds immediately in a SoFi Bank account and access cash around the clock without holding SoFiUSD. That is the bank’s product claim. The September release names no live outside merchant settlement customer and says discussions with large US merchants continue. Its April platform announcement described business deposit accounts, continuous fiat and token transfers, and mint-and-burn conversion as capabilities the platform would include.
In the arrangement SoFi describes, the merchant’s usable balance is held in a bank account while the stablecoin moves value through settlement. That division could spare a business from managing a token wallet. Actual outside-merchant use and measured cash-availability gains would show how far the capability extends beyond SoFi’s own card program.
Account dollars and token rights
A merchant paid into a bank account and a party receiving SOFID on-chain hold different claims. The issuer’s redemption and risk terms govern the token holder; the card transaction itself does not make the shopper or merchant a direct redemption customer.
SoFi Bank, a nationally chartered bank regulated by the Office of the Comptroller of the Currency, issues SoFiUSD and describes it as intended for one-for-one dollar redemption. Under SOFID’s terms, direct redemption is available only to approved SoFi customers with separate agreements, subject to conditions and fees. Receiving the token on-chain does not transfer that issuer claim. The terms also allow delays or suspensions under specified conditions.
Bank deposits and tokens carry different protections. SoFi’s product disclosure says SoFiUSD itself is not a deposit, lacks FDIC and SIPC insurance and may be subject to delay, disruption or permanent loss. A bank-account payout may be useful precisely because the merchant can receive dollars without taking those token-holder risks.
The reserve terms add another distinction. SoFi’s September release describes the token’s reserves as primarily cash. The issuer’s terms also permit cash equivalents and other legally allowed liquid instruments, with no fixed composition promised at every point. The release describes the backing policy but provides no point-in-time reserve breakdown.
The terms also exclude people and entities located in, resident in or subject to UK or European Economic Area laws from acquiring, holding, transferring or using SOFID. Token eligibility and ordinary card acceptance follow different rules. That restriction concerns token participation; it does not establish a ban on card purchases in those markets.
The scale the networks can actually show
Mastercard outlined a broader settlement menu in June: regulated stablecoins alongside additional fiat timing options. It said USDC had supported early on-chain settlement in select markets and named Paxos-issued coins, RLUSD and SoFiUSD for planned support across multiple networks. SoFi’s launch puts one bank-issued coin into use within that wider strategy. Mastercard has not disclosed the eventual traffic share of each token or said every planned pairing is live.
Visa offers a separate measure of scale. It reported on Sept. 8 that stablecoin settlement volume had recently exceeded a $20 billion annualized run rate. That reported run rate tracks stablecoin settlement activity. SoFi’s projected figure covers future annualized card-program volume after migration, so the two figures cannot rank the networks’ current stablecoin settlement volumes.
SoFi and Mastercard have moved a named bank-issued stablecoin from a proposed card-settlement option to a live one. The next evidence that would establish its wider consequence is actual token-settled volume, outside-merchant adoption and measured access to spendable cash. Until those results are disclosed, the working route is clearer than its commercial scale.
Banking,Featured,Payments,Stablecoins,Mastercard,payments,stablecoins,USDC,VisaMastercard,payments,stablecoins,USDC,Visa#Mastercards #billion #crypto #expansion #isnt1790167682
